

Shareholders of ESAB would probably like to forget the past six months even happened. The stock has dropped 40.1% and now trades at a new 52-week low of $64.48. This might have investors contemplating their next move.
Is now the time to buy ESAB, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is ESAB Not Exciting?
Despite the more favorable entry price, we don’t have much confidence in ESAB. Here are three reasons we avoid ESAB, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
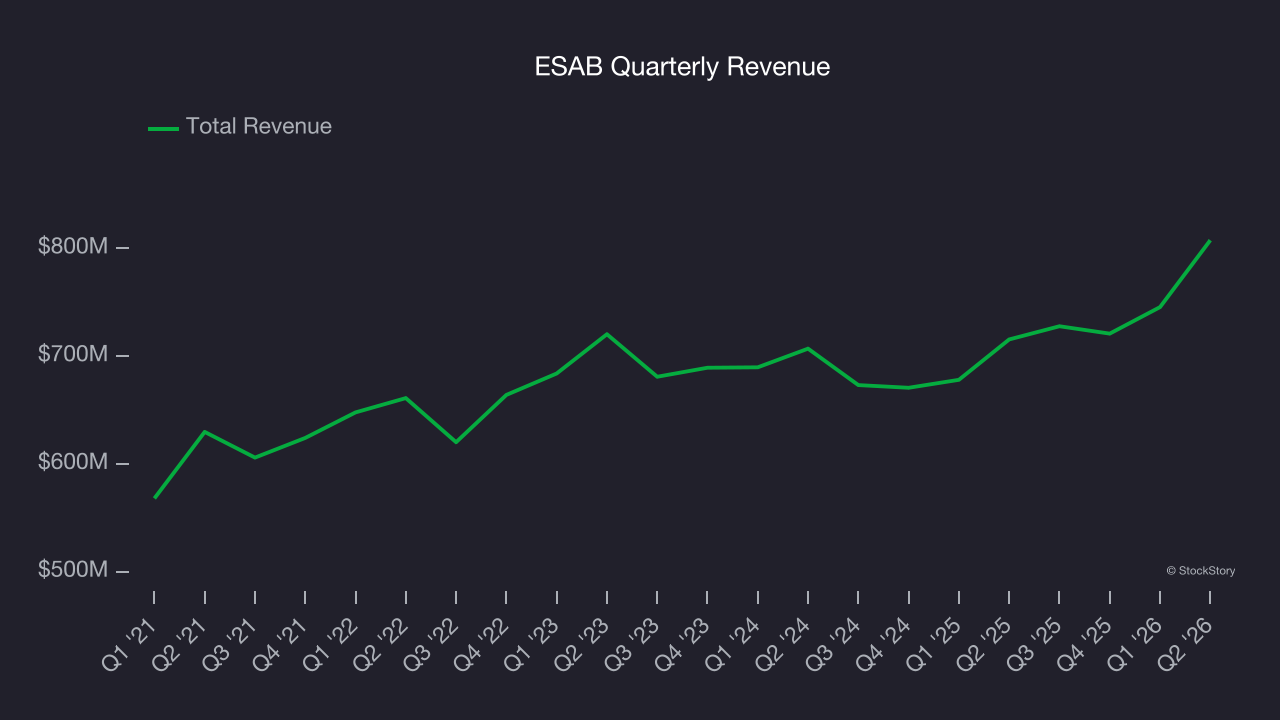
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, ESAB grew its sales at a tepid 5.3% compounded annual growth rate. This fell short of our benchmark for the industrials sector.
2. Core Business Falling Behind as Demand Plateaus
Investors interested in Professional Tools and Equipment companies should track organic revenue in addition to reported revenue. This metric gives visibility into ESAB’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, ESAB failed to grow its organic revenue. This performance was underwhelming and implies it may need to improve its products, pricing, or go-to-market strategy. It also suggests ESAB might have to lean into acquisitions to accelerate growth, which isn’t ideal because M&A can be expensive and risky (integrations often disrupt focus). 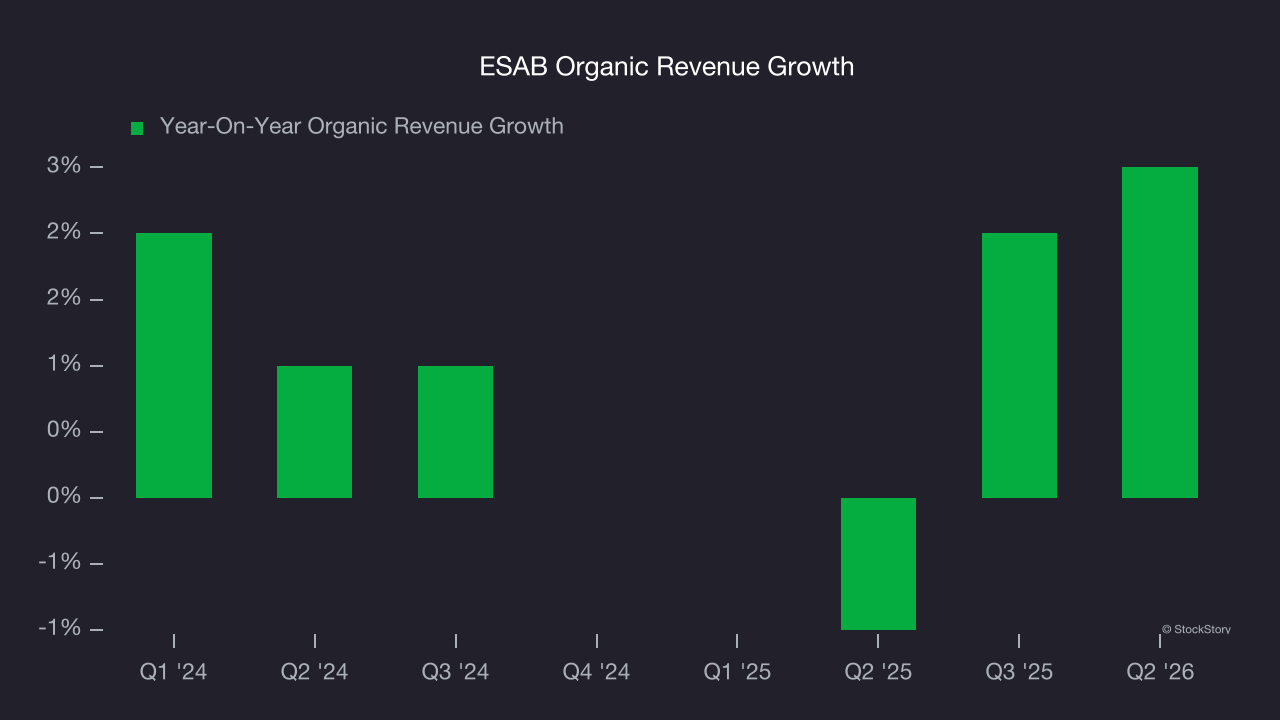
3. New Investments Fail to Bear Fruit as ROIC Declines
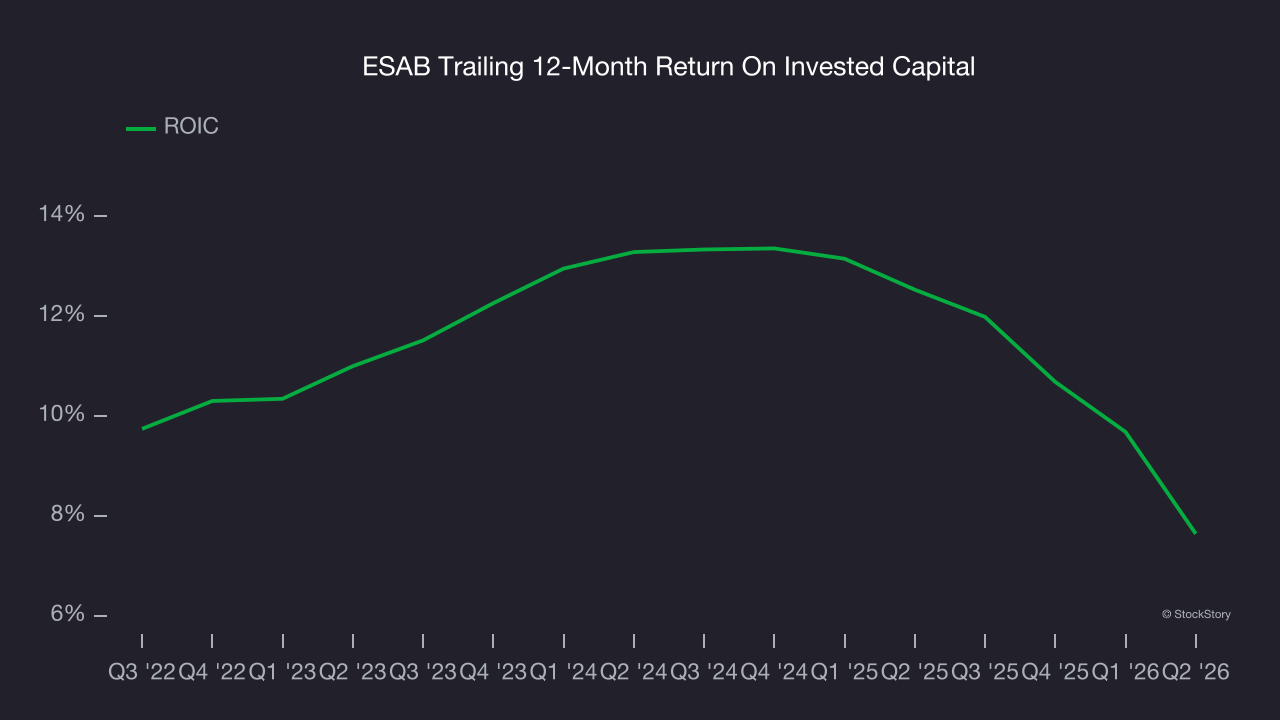
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Unfortunately, ESAB’s ROIC averaged 2.1 percentage point decreases each year over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
ESAB isn’t a terrible business, but it doesn’t pass our bar. After the recent drawdown, the stock trades at 11.2× forward P/E (or $64.48 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.